Key takeaways
- Each tax authority sets its own bank account, reference, currency and deadline, and a wrong reference can make a payment late.
- Reconcile by matching every payment to a return period, keeping remittance proofs and tracking refunds and credits by country.
- EU OSS allows one VAT payment for covered sales, and tools such as Taxually OneTax can combine payments to several authorities into one.
In short: Paying VAT in several countries means meeting each tax authority's own bank account, payment reference, currency and deadline rules, then matching every payment to the right return. The safest way to automate it is to fund payments from one place, let software apply the correct reference to each authority and keep proof of every payment. In the EU, the One Stop Shop (OSS) already lets you pay VAT for many countries in one payment.
Updated October 2026: This guide reflects the Dutch Tax Administration's move to new Rabobank accounts for business taxes from 1 May 2026 and current UK late payment penalty rules.
Why are cross-border tax payments hard to manage?
Cross-border tax payments are hard because every tax authority sets its own payment rules, and a small error can make a correct payment count as late. A business registered for VAT in five countries pays five authorities, on five calendars, often in several currencies. The common problems are:
- Currencies. Many authorities expect payment in their local currency, so you buy currency for each payment and carry the foreign exchange (FX) cost and risk.
- Bank details. Each authority, and sometimes each local tax office, has its own account. Details can change.
- Payment references. Each authority uses its own reference format. A missing or wrong reference delays matching.
- Deadlines. Due dates differ, and many authorities count a payment as made only when it reaches their account.
- Local banking. International transfers take longer and can carry fees that reduce the amount received.
- Reconciliation. You must match each payment to a return period and track refunds and credits in each country.
Take a seller registered for VAT in the UK, the Netherlands and Germany. Each quarter it makes three transfers, to three banks, with three reference formats. If it pays in pounds and euros from a US dollar account, it also buys currency three times at three different rates. A single wrong reference can leave a payment unmatched while the deadline passes.
What do tax authorities require when you pay VAT?
Tax authorities require you to pay into their account, quote their reference and get the money there by the deadline. The examples below come from official sources and show how much the details vary.
| Authority | Where to pay | Reference to quote | Timing note |
|---|---|---|---|
| UK (HMRC) | HMRC VAT account at Barclays; overseas payers use IBAN GB36BARC20051773152391, BIC BARCGB22 | 9-digit VAT registration number, no spaces; 14-character reference starting with X for penalties | Faster Payments usually arrive the same or next day; Bacs takes 3 working days |
| Netherlands (Belastingdienst) | Rabobank account NL04 RABO 0200 1122 44 for VAT from 1 May 2026; BIC RABONL2U | The payment reference (betalingskenmerk); for OSS returns, the return's reference (meldingskenmerk) | Without the reference, processing takes longer |
| Germany (Finanzamt) | Each tax office has its own account at the Bundesbank | Tax number, tax type and period | A transfer counts as paid on the day the tax office's account is credited |
| EU OSS (any member state of identification) | The member state where you are registered for OSS | The unique reference number of the OSS return | Pay with the return, by the end of the month after the period |
Always check the current details before paying. The Netherlands switched its business tax accounts from ING to Rabobank on 1 May 2026, so saved bank details went out of date. Our VAT manuals summarise the rules country by country.
What happens if a VAT payment is late or has the wrong reference?
A late payment usually triggers interest and penalties, and a payment with a wrong or missing reference can be treated as late. Some examples:
- UK. For VAT periods starting on or after 1 January 2023, HMRC charges no penalty for the first 15 days. It then charges 3% of the tax outstanding at day 15, a further 3% of the amount still unpaid at day 30, and from day 31 a daily penalty at 10% a year. Late payment interest runs from the first day overdue.
- Germany. Under section 240 of the Fiscal Code (Abgabenordnung), a late payment surcharge of 1% applies for each started month, on the tax rounded down to the nearest €50.
- EU OSS. If a reference is missing or does not match a return, the member state may return the payment. It then counts as late if you miss the deadline when you pay again.
How can you fix common cross-border payment problems?
Most payment problems can be fixed with better data and a single, controlled payment process. The table pairs each challenge with a practical fix.
| Challenge | Practical fix |
|---|---|
| Paying in many currencies | Fund all payments in one currency and lock the exchange rate before the payment run |
| Changing bank details | Keep one maintained list of authority accounts and check it before each run |
| Reference errors | Generate references from the filed return rather than typing them |
| Different deadlines | Use one calendar per country, and pay early enough to cover bank transfer times |
| Bank fees reducing the amount | Choose payment routes where the authority receives the full amount |
| No proof of payment | Store the bank confirmation with the return for each period |
Does OSS let you make one VAT payment for the whole EU?
Yes, for the sales it covers. Under the EU One Stop Shop, you file one OSS return and make one payment to your member state of identification. That state passes the VAT on to each member state of consumption. The European Commission's OSS guidance sets out these rules:
- The return is generally made out in euro, although some member states of identification can require their own currency.
- Quarterly OSS returns and payments are due by 30 April, 31 July, 31 October and 31 January. The import scheme (IOSS) uses monthly periods.
- Amounts are not netted between countries. A negative balance for one country is never set against VAT due to another.
- The member state of identification cannot offer payment plans. You arrange those with each country of consumption.
- A reminder is sent on the tenth day after a missed payment. Reminders for three consecutive periods without full payment within 10 days can lead to exclusion from the scheme, unless each unpaid amount is under €100.
OSS only covers certain sales, such as distance sales of goods to EU consumers. Local VAT registrations, for example for stock held in another country, still need local returns and local payments. Our guide to EU VAT, OSS and IOSS for distance selling explains what falls inside the scheme.
How should you reconcile tax payments across jurisdictions?
Reconcile tax payments by matching every payment to a specific return and period, then confirming that each authority shows the same balance as your books. These practices help:
- Match payment to return period. Record the country, tax type, period and reference with each payment.
- Keep remittance proofs. Save the bank confirmation and any authority receipt next to the filed return.
- Record FX separately. Note the rate used and any exchange difference, so the tax amount stays clean in your ledger.
- Track refunds and credits. Log every refund claim and credit balance by country until it is paid out or used.
- Check authority statements. Compare your records with the online account at each authority after every cycle.
- Follow up unmatched items quickly. A payment the authority cannot match may be returned and can become late.
What should you look for in a tax payment solution?
Look for a solution that reduces the number of payments you make, fixes your FX cost and shows where every payment stands. Useful features include:
- one funding payment that covers several tax authorities
- payment in a currency you choose, with a fixed exchange rate
- checks on references and beneficiary details before money is sent
- live status for each payment, from funding to receipt
- links between each payment and the return it settles
- a record of payment proofs for audits
- coverage of the countries where you are registered
How does Taxually handle multi-country VAT payments?
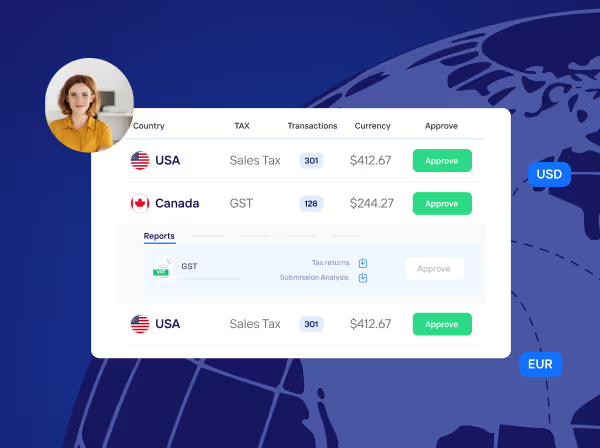
Taxually handles multi-country tax payments through OneTax, an optional service for CrossTax clients where Taxually acts as fiscal representative. With OneTax you:
- make a single bulk payment, in one currency you choose, to cover several tax authorities
- get an exchange rate fixed for two weeks
- follow the live status of each payment
- benefit from reference and beneficiary checks before payments are made
- manage payments from the VAT Payments tab in Taxually
OneTax covers 30 countries: Australia, Austria, Belgium, Canada, Cyprus, Estonia, Finland, France, Germany, Greece, Hong Kong, Ireland, Italy, Japan, Latvia, Lithuania, Luxembourg, Malta, the Netherlands, New Zealand, Poland, Portugal, Singapore, Slovakia, Slovenia, Spain, Sweden, Switzerland, the UK and the US. It is available only where Taxually is your fiscal representative.
Sources
Frequently asked questions
How do you automate tax payments for multiple jurisdictions?
Fund payments from one place, let software apply each authority's bank details and payment reference, and link every payment to the return it settles. In the EU, OSS already lets you pay VAT for many countries in one payment to your member state of identification.
Why are cross-border VAT payments rejected or delayed?
The usual causes are a missing or wrong payment reference, out-of-date bank details and transfers that arrive after the deadline. Under OSS, a payment that cannot be matched to a return may be returned and then count as late.
Can I pay VAT for several EU countries in one payment?
Yes, for sales covered by the One Stop Shop. You make one payment with your OSS return to your member state of identification, quoting the return's unique reference, and that state passes the VAT on to the other countries.
Do I have to pay foreign VAT in the local currency?
Often yes. OSS returns are generally made out in euro, although some member states of identification can require their own currency. Paying in many currencies adds FX cost, which is why some businesses fund payments in one currency with a fixed rate.
What is the penalty for paying UK VAT late?
For VAT periods starting on or after 1 January 2023, HMRC charges 3% of the tax outstanding at day 15, a further 3% of the amount still unpaid at day 30, and a daily penalty at 10% a year from day 31. Late payment interest also applies.
What is Taxually OneTax?
OneTax lets CrossTax clients where Taxually is fiscal representative pay tax in 30 countries with one bulk payment in a currency they choose. The exchange rate is fixed for two weeks, and each payment's status is shown live.